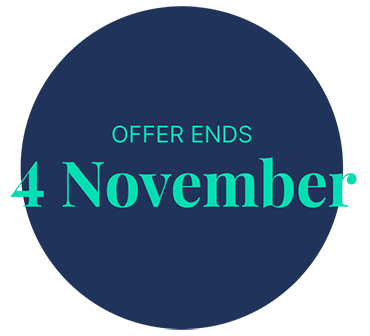
New fund launch. £1 per unit fixed offer price until the end of the offer period on 4th November 2026 (may close early).
HL MONEY MARKET FUND
The UK’s lowest-cost Money Market Fund
0.06% ongoing charges figure, the lowest of any Money Market Fund in the UK (HL annual account charge of 0.35% also applies)
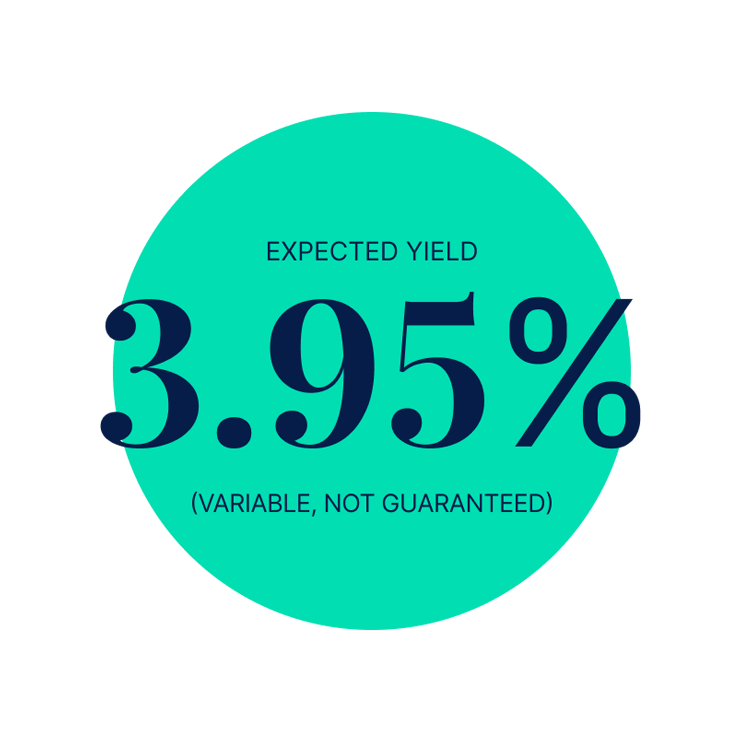
Exclusive to HL clients, with one of the highest expected yields in the market*, currently 3.95% (variable and not guaranteed)
Don’t tolerate inactive banks. Earn more with the new HL Money Market Fund, or get competitive rates with Active Savings
Important information: The HL Money Market Fund is a short-term money market fund. It is not a deposit account and is not guaranteed. It does not rely on external support to guarantee the value of your investment or your ability to buy and sell daily. If the fund falls in value, you could get back less than you invest. This fund is managed by Hargreaves Lansdown Fund Managers Ltd, part of the Hargreaves Lansdown Group. *Checked on 21 October 2026 against all MMFs available to retail clients.
Important information: The HL Money Market Fund is a short-term money market fund. It is not a deposit account and is not guaranteed. It does not rely on external support to guarantee the value of your investment or your ability to buy and sell daily. If the fund falls in value, you could get back less than you invest. This fund is managed by Hargreaves Lansdown Fund Managers Ltd, part of the Hargreaves Lansdown Group. *Checked on 21 October 2026 against all MMFs available to retail clients.
What is a Money Market Fund?
A Money Market Fund offers an alternative to holding cash, that aims to give you higher returns. It invests in short-term debt from governments, banks and highly rated companies, making it less risky than other types of investments.
Potential to beat cash
Aims to give you a higher return on your cash while giving you a short-term home for your money.
A lower-risk option
If you’re worried about markets or nearing retirement a Money Market Fund can reduce risk.
Diversified
Invests across a range of high-quality short-term bonds and cash like investments, helping to spread risk.
Money Market Funds vs cash
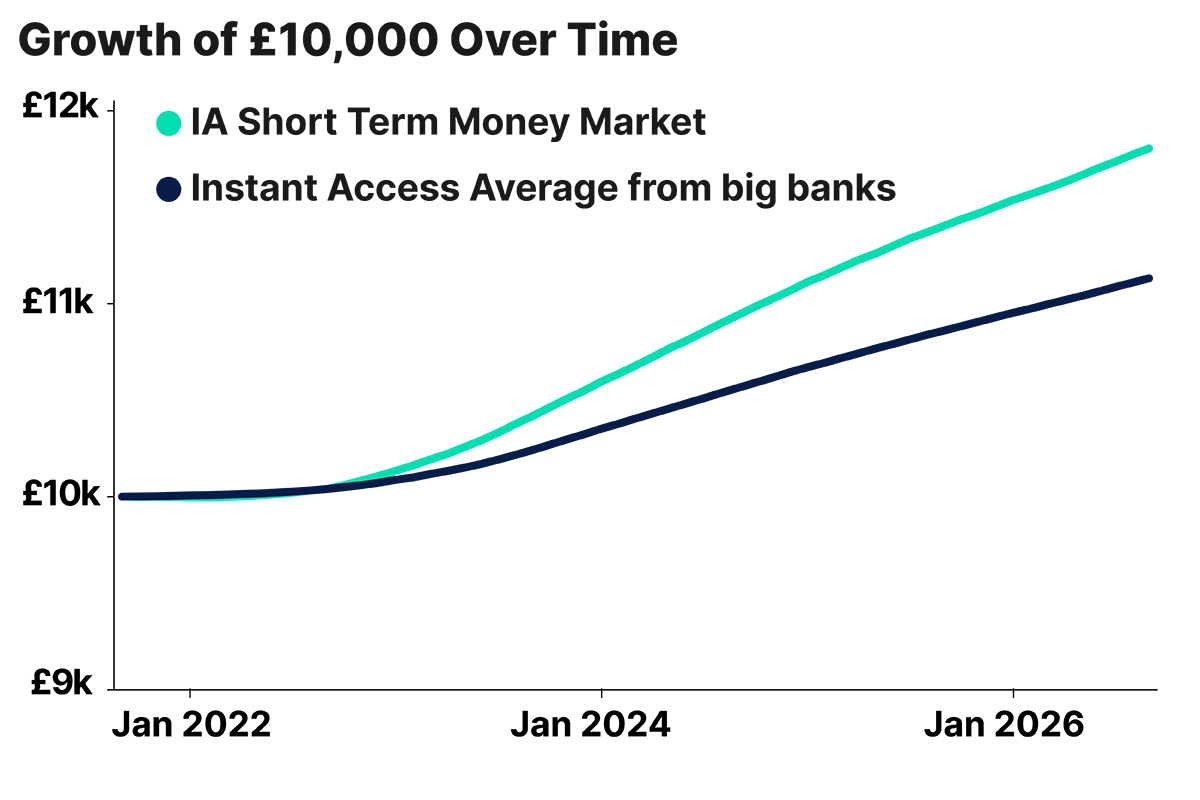
Over the last five years, Money Market Funds have typically delivered higher returns than cash held in Instant Access Savings accounts on average.
As the chart shows, £10,000 left in cash for 5 years grew to just over £11,100. Invested in a Money Market Fund over the same period, it reached over £11,800, meaning you'd get an extra £700.
Your actual returns depend on the investments you choose. Remember, investments can rise and fall, so unlike cash, you could get back less than you invest.
Past performance isn’t a guide to the future. Source: Lipper, 30 September 2026 interest rates based on the average instant access rates available on £10,000.
3.95% expected yield
Not only is the HL Money Market Fund the lowest cost in the UK, we also expect it to give one of the highest yields on the market after fund charges. The yield is variable and not guaranteed.
Why invest in the HL Money Market Fund?
The HL Money Market Fund offers a competitive yield, low costs and quick access to your money.
Managed by a specialist investment team with over 20 years’ experience running money market funds, delivering competitive returns while managing risk.
Expected yield 3.95% (variable and not guaranteed) with the lowest ongoing charges in the UK.
Quick settlement - sell before 8am and your money will be in your investment account by the afternoon.
Make sure you read the Fund Prospectus, along with the key information below. Money Market Funds are low risk, but it is still an investment, meaning its value has the potential to rise or fall, so you could get back less than you put in.
How to invest in the new HL Money Market Fund
The exclusive HL Money Market Fund offer period starts on 21 October 2026
Order by 11.59 pm on 3 November 2026 to receive the £1 per unit fixed offer price (unit price variable after this period).
When the fund goes live on 4 November, your purchase will be finalised at the offer price and will appear in your account.
You can invest lump sums from £100. Direct Debit investments (from £25 per month) are available but will not be valid to receive the £1 fixed offer price.
If the fund is popular the offer period may close early.
Is a Money Market Fund right for you?
A Money Market Fund could be worth considering if:
You have cash you want to work harder while you decide what to do next, or you're looking for a more stable home for it in the meantime.
You want quick settlement, so you can move investments when you want to.
You’re approaching retirement and want to hold the fund in your HL SIPP to help reduce risk while aiming to earn more than you might by holding cash.
You’re looking for a relatively low-risk, short-term investment.
You understand that the value of investments can rise and fall, so you could get back less than you invest.
This isn't personal advice or a recommendation to invest. If you're not sure what's right for you, ask for financial advice.
FAQs
It’s easy to make the most of the £1 per unit price offer, you just need to make sure you have a relevant account and that it’s topped up before the offer period starts on 21 October 2026.
You can then log into your secure online account and select the HL Money Market Fund, entering the value you’re looking to invest. Next, you’ll be provided with the details of the deal for you to check; if you are happy, you can confirm and the deal is done. Alternatively, you can give one of our experienced dealers a call and buy your fund over the phone.
Make sure you have purchased your fund units before 4 November 2026 to guarantee your fixed £1 per unit fixed offer price (note that the unit price will be variable after this period). On 4 November, your purchase will be finalised at the offer price and will show up in your account as live.
If you switch out of another fund and your instruction is processed after 4 November 2026 you will not receive the £1 per unit fixed offer price and the online dealing charge of £1.95 will apply.
Yes, you can invest by Direct Debit. You can set up a Direct Debit from as little as £25 per month. We’ll take payments on the 7th of the month or next available working day and invest by the 10th of the month or next available working day.
To set up your direct debit, log in to your account and go to the ‘Monthly Savings’ tab within an existing account via our website, or via the ‘Direct Debit’ section in the HL app. You can also set up an instruction when opening an account.
The first investment by Direct Debit will be made in November but it won’t receive the per unit launch price of £1. Instead, you’ll pay the price based on the value of the fund at the time, which could be lower or higher than £1. If you’re setting up a new Direct Debit, you’ll need to have this done by 29 October for the first investment to be made in November.
If you invest in the fund at launch, you will receive your first income payment on 31 December 2026. The fund manager calculates income on the 1st of the following month, and any income due is paid on the last day of that month. If you invest in the accumulation share class, any income generated will be reinvested in the Fund, increasing the price of each unit.
You can buy and hold the HL Money Market Fund in any of our investment accounts.
If you want to see all the options, and their risks and benefits, try our compare accounts tool.
The ongoing charge covers management and all expenses except transaction costs, which all funds incur when buying or selling bonds and which are reflected in the fund price. The charge is deducted from the fund’s income, not its capital.
Income distributions are generally taxable as interest income in the tax year received. For Accumulation units the income is usually still taxable as interest, even though it is rolled up into the fund rather than paid out.
You can check the current yield for the HL Money Market Fund after launch by viewing the fund factsheet. The yield is variable and not guaranteed.
The type of unit you hold determines how any income generated from the fund's underlying investments is treated.
With income units, income is paid out to fund holders as cash. This could provide the investor with an income stream or the cash could be reinvested to buy additional units.
With accumulation units income is retained within the fund and reinvested, increasing the price of the units. Generally, for investors who wish to reinvest income, accumulation units offer a more convenient and cost-effective way of doing so.
HL Money Market Fund
Start investing in the exclusive HL Money Market Fund today.