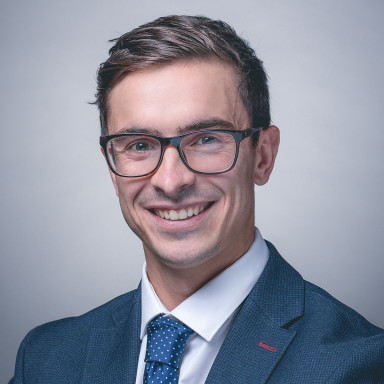
We have a high level of conviction in all three experienced co-managers – Adrian Frost, Nick Shenton and Andrew Marsh
The managers invest in cash generative businesses with the potential to grow their earnings, and dividends, for years to come
The fund has performed well compared to the FTSE All-Share over the long term and consistently provided a growing income alongside a yield premium to the index
The fund features on our Wealth Shortlist of funds chosen by our analysts for their long-term performance potential
How it fits in a portfolio
The Artemis Income fund invests mainly in large UK companies, with some holdings in medium-sized and overseas companies, too. The managers look for companies that they believe will deliver a resilient income, though there are no guarantees.
We view this as a more conventional UK equity income fund that could work well alongside other asset classes in an income-focused portfolio. It could also complement a portfolio focused on growth, where investors who don’t need the income can benefit from the compounding effect of reinvesting it.
Manager
Artemis Income is managed by the experienced trio of Adrian Frost, Nick Shenton and Andy Marsh.
Frost is an industry stalwart and one of the most well-known UK equity fund managers around. He began his career in 1983 at Deutsche Asset Management and in 2002, he joined Artemis to run this income fund.
Shenton joined Artemis in 2012 to work alongside Frost as manager of the fund. His career began in 2003, working at F&C Asset Management and Polar Capital before joining Artemis.
Marsh joined Frost and Shenton at Artemis in 2018. His career began at accountancy firm Ernst & Young in 1997. He held a number of different roles before becoming a fund manager at Polar Capital in 2006, where he worked until joining Artemis.
The managers have more than nine decades of investment experience between them and have developed a strong working partnership. They’ve been investing through good times and bad, and we think their skillsets make them one of the best teams in the business. We have a high level of conviction in all three managers.
Process
The managers aim to outperform the FTSE All-Share over the long term, while providing a growing income and a dividend yield above what’s offered by the index.
This means that the management trio look for businesses that they believe can pay a stable and resilient level of income, through the market cycle, regardless of the economic backdrop. Key to this is a company’s ability to generate free cash flow, an area of focus for the team. They seek companies with recurring revenues which they believe will still have consumers, profits, and therefore dividends, in the future, regardless of disruption – although nothing’s guaranteed.
The managers spend a lot of time assessing company management and think that their ability to allocate capital efficiently is vital to making a success of the business. There’s also analysis of the structure of different industries, how value’s created within them and which companies have the best competitive position to take advantage.
They aim to have a portfolio of between 45 and 55 companies with diversified cash flows, and therefore a diversified income stream. Most of the fund invests in larger companies, with 83.1% of its assets currently invested here. At a stock level, the larger positions in the fund include the likes of insurer Aviva, banks Natwest, Lloyds and Barclays, and healthcare company GlaxoSmithKline (GSK).
In terms of sector exposures, the biggest investment is in financials at 33.1%, followed by consumer discretionary and consumer staples stocks at 18.5% and 13.6%, respectively.
In recent months, the managers have made a number of changes to the fund. They have sold information and software company Wolters Kluwer after concerns that their software could be displaced by developments in AI. They sold industrial company Spectris after it received a takeover offer from private equity company KKR.
On the other hand, the managers have made a number of new investments. This includes sports nutrition company Glanbia, most known for their nutrition brand Optimum Nutrition. The team believe that consumers are becoming more aware of the benefits of increasing protein in their diets and Glanbia have a competitive advantage to benefit from this. They also bought beverage company Diageo following the appointment of previous Tesco CEO Dave Lewis. The managers believe that he’ll be the catalyst for Diageo to be run more efficiently.
ESG Integration
Investment teams across Artemis are encouraged to think for themselves and invest according to their own style, so approaches to ESG integration across the firm vary. Meetings with the Artemis teams that we back on the Wealth Shortlist suggest ESG is an important factor.
Artemis has a firm-wide policy to support the aims of international conventions on cluster munitions and antipersonnel mines and therefore the firm will not knowingly invest in companies which produce these weapons. The firm also avoids companies involved in biological/chemical weapons, blinding laser weapons, incendiary weapons, weapons that produce non-detectable fragments, and depleted uranium, as well as companies with a tie to nuclear weapons in countries not included in the Treaty on the Non-Proliferation of Nuclear Weapons. Companies that grow or sell cannabis are also avoided.
Artemis votes on all its holdings, unless restricted from doing so, and fund managers lead engagement with firms to develop their understanding, raise issues with management and monitor subsequent developments. The firm provides engagement case studies, and other information about its engagement and voting efforts, in an annual Stewardship report. Artemis also provides a monthly voting summary, which includes rationales for votes against management and abstentions. Stewardship activity is carried out in line with the firm’s comprehensive Stewardship policy.
We think that ESG-related risks are suitably considered as part of the stock selection process. That said, the fund may still invest in companies from industries such as tobacco or oil & gas.
Culture
Artemis provides an attractive environment for fund managers, allowing them the freedom to run money how they see fit without imposing a house view on them. It’s also a collegiate atmosphere, with managers supporting and challenging one another. The managers of the fund are partners in the business. We think that this structure is a good thing for investors, as the managers and the firm are focused on the long term and can run funds without distractions from short-term shareholder demands. They are rewarded from the profits of the business, based on their long-term fund performance, and payment of the profit share can be deferred over several years.
Cost
This fund has an ongoing annual charge of 0.80%, but we've secured HL clients an ongoing saving of 0.21%. This means that you pay a net ongoing charge of 0.59%. The fund discount is achieved through a loyalty bonus, which could be subject to tax if held outside of an ISA or SIPP. Our platform charge of up to 0.35% per year also applies, except in the HL Junior ISA, for which no platform fee applies.
Both a buy and sell instruction will be subject to HL dealing charges. Find out more about our charges.
The fund takes charges from capital, which can increase the yield but reduce the potential for capital growth.
Performance
The fund has outperformed the broader FTSE All-Share Index since Adrian Frost took over as manager in 2002. Over this period, its delivered returns of 604.7%** to investors, well ahead of the 458.8%* return from the FTSE All-Share index, and the IA UK Equity Income peer group average return of 449.1%.
However, during the last 12 months, the fund delivered returns of 15.4%, underperforming the FTSE All-Share Index and the IA UK Equity Income peer group average, which returned 21.3% and 18.9%, respectively.
The vast majority of the underperformance occurred in the first quarter of 2026. The initial underperformance was driven primarily by fears that AI will disrupt many software-related businesses. Investors instead preferred commodity-related businesses that were benefiting from higher metal prices as the demand for AI data centres has continued to increase. As a result, owning the likes of data and software companies Pearson and RELX hurt performance, as did not owning mining companies Glencore and Rio Tinto.
We also saw the effects that the US war with Iran had on the fund. Events organiser Informa and airline EasyJet both detracted as investors expected that disruption in the Middle East and higher jet fuel costs would weigh on demand for both businesses. Not owning defence contractor BAE Systems also detracted, as it performed well following the tension in the Middle East.
On the other hand, during the last 12 months, a number of companies also performed well. UK banking companies Lloyds and NatWest continued to do well as higher interest rates have bolstered their profitability. Copper mining company Anglo American was another strong performer, benefitting from rising copper prices.
The managers have also historically delivered a yield above the FTSE All-Share and have grown income payments over time. The fund currently yields 3.34%, compared with 3.06% for the FTSE All-Share. Income is not guaranteed, though, and yields can rise and fall and are not a reliable indicator of future income.
** Please note that this data is for Class R units in order to show performance since Frost became manager. The performance noted below is using Class I units, which are available to investors with HL and have lower ongoing charges.
Annual percentage growth
31/08/2021 To 31/08/2022 | 31/08/2022 To 31/08/2023 | 31/08/2023 To 31/08/2024 | 31/08/2024 To 31/08/2025 | 31/08/2025 To 31/08/2026 | |
|---|---|---|---|---|---|
Artemis Income | -0.68% | 5.71% | 22.54% | 15.12% | 15.44% |
FTSE All-Share | 1.01% | 5.23% | 16.98% | 12.58% | 21.30% |
IA UK Equity Income | -2.86% | 3.85% | 18.35% | 8.03% | 18.91% |