Hal Cook, senior investment analyst, Hargreaves Lansdown:
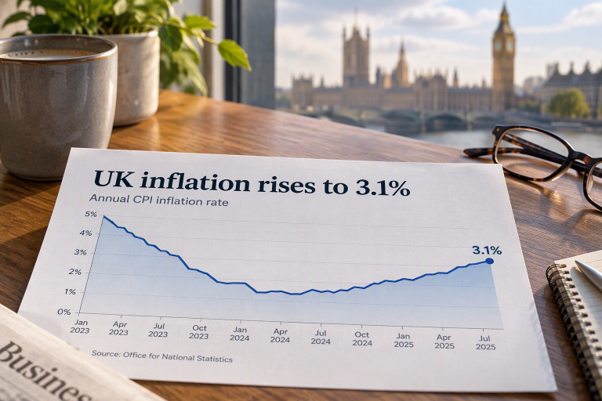
“A lack of any de-escalation of the Iran war has caused oil and gas prices to rise from the lows of early July. With the energy price cap increase coming in October, inflation is expected to increase further from here, too.
This means that the most recent forecast from the Bank of England (from 30 July), which predicted inflation would increase to 3.2% before the end of 2026 before falling back again in 2027, was always likely to underestimate the actual inflation outturn.
And there are other risks that might cause inflation to go even higher down the line. This includes the current El Nino weather pattern, which has potential to hit crop yields in 2027.
That’s a headache for the Bank. Rates have been broadly expected to sit at 3.75% until 2027, but higher inflation adds weight to the three MPC members who think rates should be increased. Adding economic growth of 0.4% in July, compared to forecasts of 0%, makes the decision to increase rates to 4% before year-end even more likely.
But even if the Bank holds interest rates tomorrow, higher inflation and higher interest rates support the rising gilt yields seen in recent weeks and make it less likely that those yields will fall much again any time soon.”
Alice Haine, head of personal finance, Hargreaves Lansdown:
“It’s back to school with a sting in its tail for households as the traditional September reset gets off to a rocky start. This is the time when many are looking to trim spending and boost savings in the run-up to Christmas. Rising prices, particularly on fuel and energy, make that considerably harder, with more income swallowed up by essential bills, leaving less room to save and invest for the future.
HL research* shows that more than half of Britons (55%) would cut back on spending if everyday living costs were to increase and almost three in ten (27%) would save less. More encouragingly, more than one in 10 (11%) already recognise the importance of boosting their savings in challenging times, saying they would save more if everyday living costs rose dramatically.
Savers may have been enjoying more competitive savings rates of late, but the benefit only applies to those who actively shop around for the best deals. Anyone whose money is sat languishing in an account with an ultra-low rate is losing real value every month.
Savings platforms, like Active Savings, make it easy to shop around for a competitive savings account as savers can compare rates from a range of banks and building societies in one place.
While rising bills will feel all too familiar for households still recovering from the darkest days of the cost-of-living crisis, building a healthy emergency fund is one of the best ways to strengthen financial resilience. As a rule of thumb, those of working age should aim for at least three months’ worth of essential expenses in cash, while for retirees it’s between one and three years’ worth.”
Helen Morrissey, head of retirement analysis, Hargreaves Lansdown:
“Today’s inflation figure holds valuable clues as to what level the state pension may sit at next year. Next month’s inflation figure is the final piece in the triple lock puzzle and, barring a real surge, we’re likely to see average wage data delivering an inflation-busting increase of 3.9% next April.
Such an increase would put someone on the full new state pension on course to receive £250.70 per week from next April, up from £241.30. Someone on a full basic state pension would receive £192.10 per week – up from £184.90.
It’s a good foundation, but it will only cover the basics and the HL Savings and Resilience Barometer shows that only 43% of households are currently on track for an adequate retirement income.
If you want more from your retirement years, such as travel and days out with loved ones, then you need to make the most of your pensions to build a good level of retirement income. Check to see if you can increase your contributions and whether your employer can increase theirs in turn. Even making small steps can make a huge difference.”
* Survey of 2,000 people carried out by Opinium in June 2026
Notes to Editors
HL is the UK’s largest investment and savings platform for private investors and more than 2.2 million clients trust us with £205 billion (as of June 2026).
We help Britain build wealth, with confidence. Our promise is simple: to provide the best products, the best support and the best value. Founded in 1981, we’ve been helping people save and invest for a better financial future for more than four decades. We offer a lifelong, secure home for our clients’ investments and savings, combining great value with outstanding service, to make managing your money easier at every stage of life.
Our award-winning Savings & Resilience Barometer measures the nation’s financial resilience across our 5 to Thrive pillars, equipping people with the tools they need to strengthen their financial futures.
Saving and investing is for the whole family, and to support intergenerational wealth transfer, we’ve removed all platform charges and share dealing fees on our Junior ISA, meaning kids go free, and we’ve reduced the platform fee on our Lifetime ISA to 0.25%, supporting those savings for their first home or for retirement.
Regular saving into all funds, FTSE 350 shares, and selected investment trusts and ETFs is free.
Our clients also have access to the most comprehensive pension and retirement solution, including SIPP accounts, SIPP Income Drawdown, UFPLS payments and annuities, as well as over 14,000 investment options across funds, shares, ETFs, investment trusts, bonds and gilts.
HL Active Savings is the UK's largest retail cash savings platform that lets savers easily make more of their money and the HL Cash ISA allows savers to manage their Cash ISA portfolio across multiple banks, all within one account.