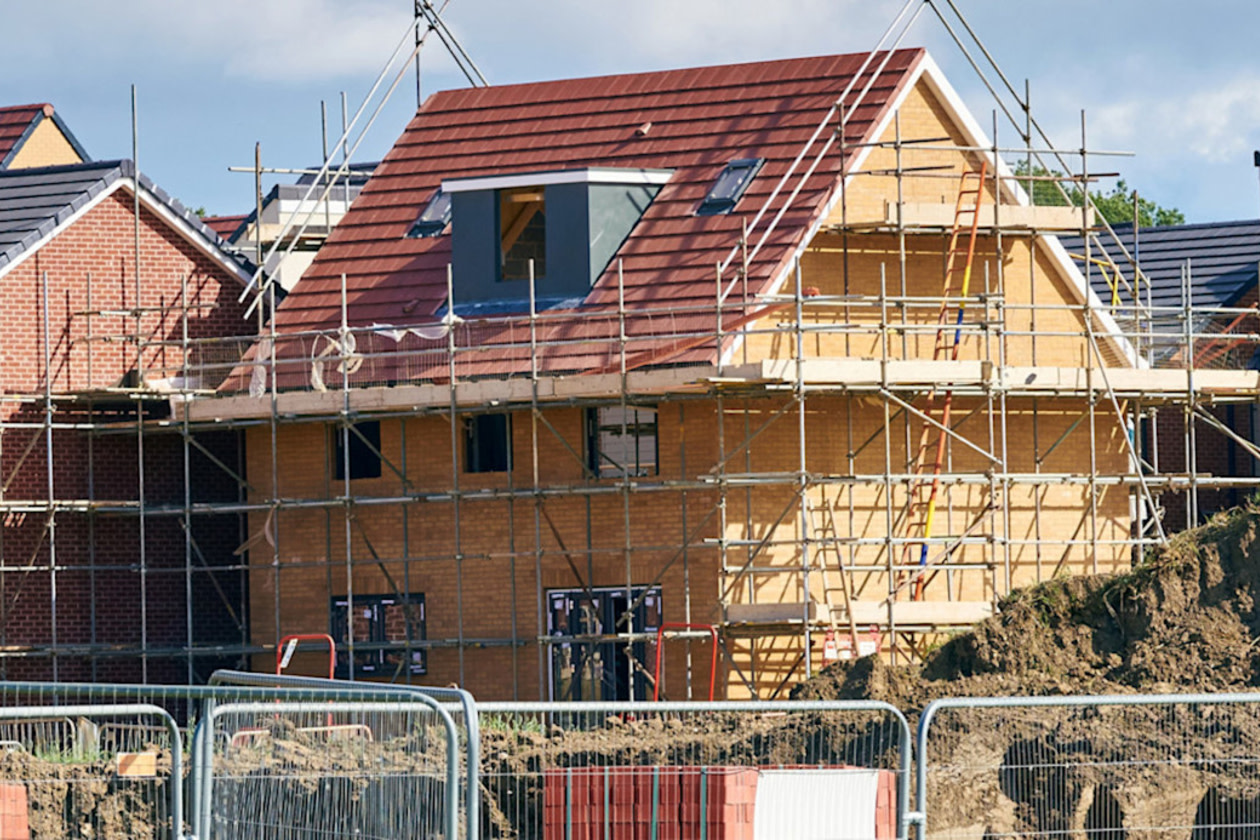
Full-year underlying revenue rose 6.6% to £6.1bn, driven by a 5.0% uplift in new home completions to 17,667 and a smaller contribution from higher average selling prices.
Adjusted pre-tax profits fell 7.1% to £0.6bn, slightly ahead of market expectations. The decline came as margins were squeezed by build cost inflation of about 2% and the increased use of buyer incentives.
Free cash flow rose from £13mn to £428mn, driven by generating cash from its existing land inventory and cutting back land investment. The net cash position remained broadly flat at £0.8bn, excluding land creditors of £0.7bn.
Full-year completions guidance was trimmed slightly to between 17,500-17,900 new homes. Build cost inflation is expected to be 3-4%.
A final dividend of 1.0p per share was announced. Shareholder return guidance for 2027 is unchanged, with £0.4bn planned primarily through share buybacks.
The shares rose 7.6% in early trading.
Our view
HL view to follow.
Barratt Redrow key facts
All ratios are sourced from LSEG Datastream, based on previous day’s closing values. Please remember yields are variable and not a reliable indicator of future income. Keep in mind key figures shouldn’t be looked at on their own – it’s important to understand the big picture.
This article is original Hargreaves Lansdown content, published by Hargreaves Lansdown. It was correct as at the date of publication, and our views may have changed since then. Unless otherwise stated estimates, including prospective yields, are a consensus of analyst forecasts provided by LSEG. These estimates are not a reliable indicator of future performance. Yields are variable and not guaranteed. Investments rise and fall in value so investors could make a loss.
This article is not advice or a recommendation to buy, sell or hold any investment. No view is given on the present or future value or price of any investment, and investors should form their own view on any proposed investment.