Management expects to report a 7.1% rise in first-half underlying profit to £166mn, with underlying earnings per share (EPS) up 5% to 16.1p (consensus: 15.2p). This was driven by like-for-like net rental growth of 12%, lettings at new developments and cost savings, which more than offset the impact of higher interest rates and fewer early lease termination payments.
Portfolio values rose 1.5% in the period, as estimated rental value growth of 3.0% offset the impact of higher interest rates.
The group completed £247mn of disposals, broadly in line with book value, with a further £202mn of assets under offer.
Full-year guidance has been reiterated, with underlying EPS expected to rise from 28.9p to at least 30.5p (consensus: 30.6p).
The shares rose 2.3% in early trading.
Our view
British Land delivered a positive update ahead of its first-half results. Double-digit rental growth highlights that demand across its portfolio remains strong, and new developments are being snapped up by tenants. Higher interest rates are pushing up borrowing costs and holding back property values, but full-year guidance looks well within reach if current momentum continues.
Commercial property can be sensitive to economic swings, with demand for space shaped by business confidence and consumer spending. But British Land’s focus on prime assets should offer some protection from weaker conditions.
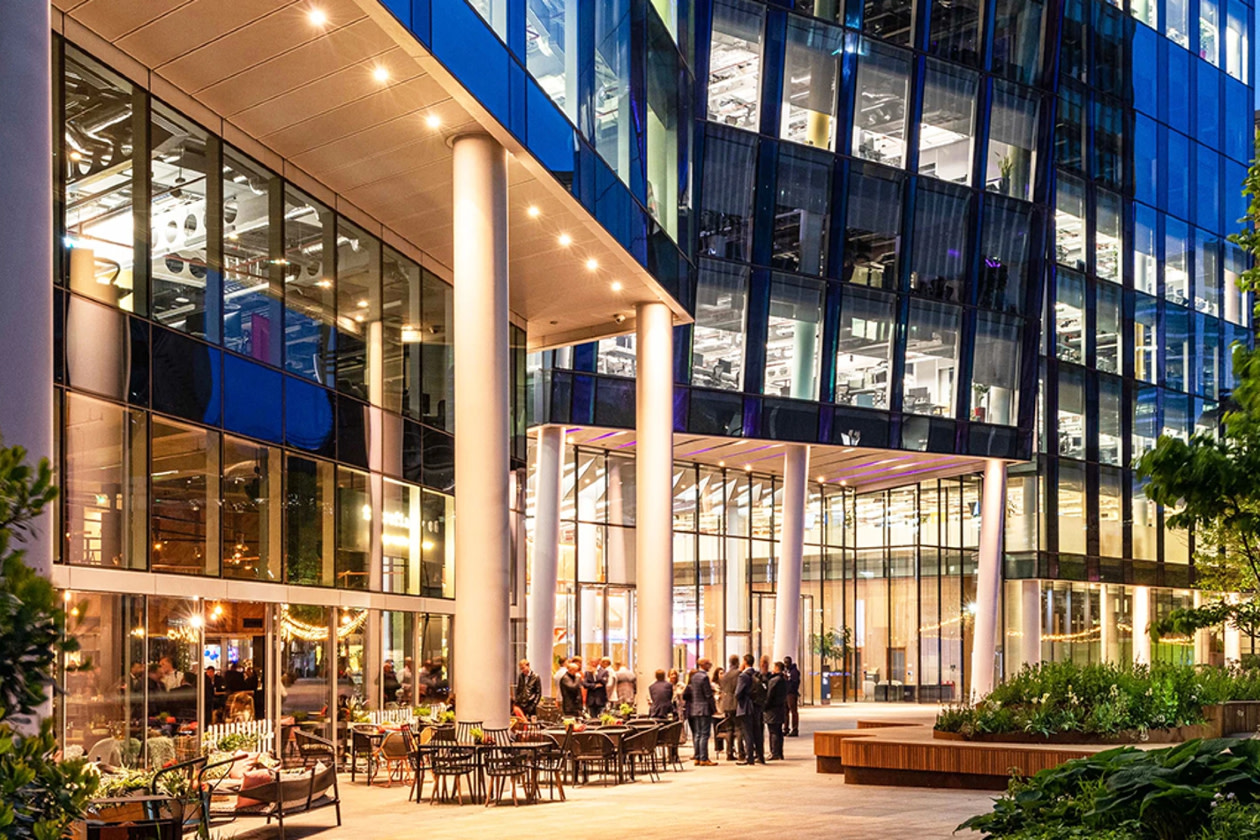
London campuses remain a priority, and the science & technology sector is a key part of this strategy. It accounts for about 35% of British Land’s campuses, but that could rise to 50% by the end of the decade. Recent progress at key sites like 1 Triton Square shows that the company is successfully attracting tenants in this fast-growing field, especially as AI fuels the sector’s momentum.
Urban logistics is another exciting growth area. The company is focusing on central London, where demand for warehouse space is high, and supply is tight. Projects like the recently completed Mandela Way multi-storey warehouse show that British Land is adapting to trends like e-commerce and same-day delivery.
Its retail parks have also been a strong asset of late, in terms of both rental growth and capital appreciation. These parks are popular with retailers because they are affordable, easily accessible, and adaptable, resulting in high occupancy rates of 99%. The group’s growing portfolio in this area is well-positioned to benefit from continued demand for out-of-town shopping locations.
Development is making a comeback, with rising rents strengthening the case for reinvesting cash from asset sales into higher-yielding urban logistics and campus projects. But signs of build-cost inflation returning should be watched carefully.
The group’s debt levels remain toward the upper end of its target range, driven by the uptick in development spending. We’re not overly concerned for now as rents and valuations are trending in the right direction, and the 6.1% forward dividend yield looks well covered. But with interest rate expectations rising, there is added pressure on new sites to perform well. Any weakness on this front could limit the pace of future dividend growth, which is never guaranteed.
British Land is well-positioned for the future. Its focus on retail parks, urban logistics, and campuses reflects a shift toward areas with the strongest growth potential, and we see scope for the current discount to book value to narrow. But the step-up in development activity brings execution risk, and any reversal in occupier demand or rise in funding costs could weigh on returns.
Environmental, social and governance (ESG) risk
Broadly, real estate is relatively low risk in terms of ESG. One of the principal drivers of this risk is the capacity to integrate material ESG considerations into decision-making, risk management and public reporting; the most material ESG considerations are environmental, like carbon emissions reduction, energy efficiency and physical climate risk. The rise of hybrid working has also reduced demand for commercial property, making product governance and customer satisfaction a top priority. Other risks to monitor include labour relations, business ethics, and emissions & waste.
According to Sustainalytics, British Land’s overall management of material ESG issues is strong.
British Land Co. Plc has a robust environmental policy, with a portion of executive remuneration explicitly tied to sustainability performance targets. The company also has an effective whistleblower program. Additionally, board-level oversight is in place for ESG matters. However, its ESG reporting does not yet fully align with leading industry standards.
British Land key facts
All ratios are sourced from LSEG Datastream, based on previous day’s closing values. Please remember yields are variable and not a reliable indicator of future income. Keep in mind key figures shouldn’t be looked at on their own – it’s important to understand the big picture.
This article is original Hargreaves Lansdown content, published by Hargreaves Lansdown. It was correct as at the date of publication, and our views may have changed since then. Unless otherwise stated estimates, including prospective yields, are a consensus of analyst forecasts provided by LSEG. These estimates are not a reliable indicator of future performance. Yields are variable and not guaranteed. Investments rise and fall in value so investors could make a loss.
This article is not advice or a recommendation to buy, sell or hold any investment. No view is given on the present or future value or price of any investment, and investors should form their own view on any proposed investment.