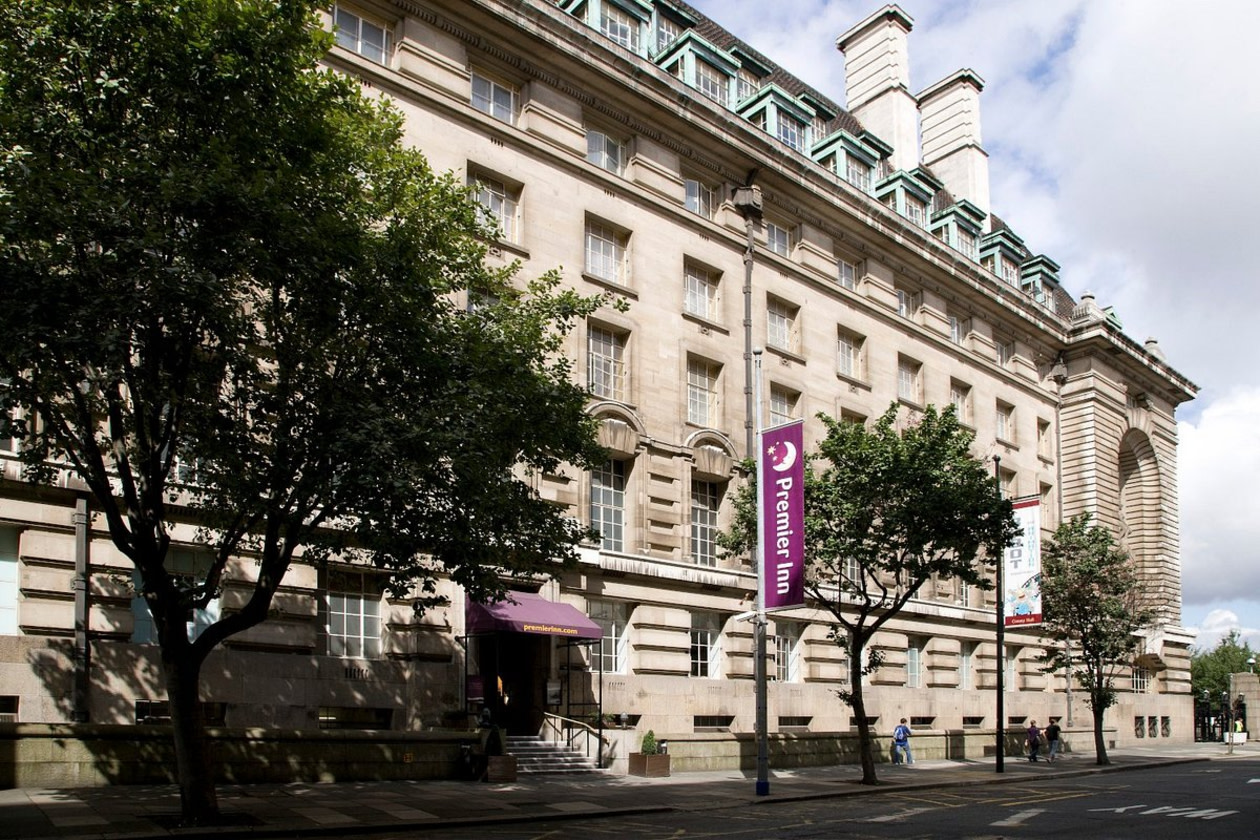
Whitbread’s first half revenue rose 2% to £1.6bn (£1.6bn expected). Premier Inn UK & Ireland sales accelerated in the second quarter, with double-digit growth in Germany largely driven by new room openings. Growth was constrained by a 9% fall in UK food and beverage sales, as the restaurant estate was reduced further.
Underlying cash profit (EBITDAR) grew 1% to £0.6bn (£0.6bn expected) as revenue growth and cost efficiencies more than offset inflationary headwinds.
Free cash flow improved 35% to £174mn largely due to a decrease in capital expenditure. Net debt including lease liabilities increased from £4.9bn to £5.3bn.
The interim dividend was flat at 36.4p per share.
Accommodation sales in the UK in the first five weeks of the second half were up 4.5% in the UK and 31.2% in Germany supported by both expansion in the estate as well as underlying growth.
The shares rose 3.2% following the announcement.
Our view
Whitbread’s Premier Inn outperformed a resilient UK hotel market in the first half, and a strong start to the third quarter was well received by investors. Meanwhile, the German business continued to scale and remains on course to deliver a second consecutive year of underlying profitability.
Premier Inn remains a powerful brand with an impressive record of market outperformance. Growth in business bookings, app usage and selective third-party distribution suggests its commercial initiatives are supporting that competitive edge.
It’s already the UK market leader, but structural shifts in the hotel industry still leave room to take share. Targets for new openings have been scaled back. While we support the sharper focus on higher-return locations, there are still concerns about whether planned greenfield investments will pay off.
Based on the latest guidance, net UK cost inflation is expected to run close to 4%, making profit growth hard to come by this year, even if demand holds up. With continued pressure on household finances and business costs, there’s limited room for complacency.
That makes delivery of the efficiency programme particularly important. Progress is encouraging, with £39mn of the £60mn full-year savings target achieved in the first half, leaving scope for the target to be exceeded if momentum continues.
The group’s updated five-year plan builds on earlier initiatives to integrate its restaurants into Premier Inn, while also targeting further profitable growth in Germany. The measures look well thought through, but execution will be critical.
Plans to reduce investment spending and release capital from the real estate portfolio, along with a £250mn increase in planned cost savings, underpin targets to distribute £2bn of free cash flow to investors by 2031.
However, annual capital expenditure is set to remain in the £0.4-0.6bn range. Freehold disposals should provide much of the funding, but we’ll need to see convincing proof that such reallocation of capital can create value for shareholders.
Management is yet to introduce a buyback this year, and no shareholder payouts can be guaranteed. If cash generation weakens, some funds may need redeploying to keep net debt within the target range.
We think Whitbread has an enviable market position, and the current valuation weakness would normally be seen as an attractive entry point. The strategy could help profitability recover over the longer term, but earnings are still expected to fall this year. Successful execution of the plan could lift sentiment, but uncertainty around demand and ongoing cost pressures leave a high risk of disappointment.
Environmental, social and governance (ESG) risk
Consumer services companies are medium-risk in terms of ESG, and very few companies are excelling at managing them. That leaves plenty of opportunity for forward-thinking firms. The primary risk-driver is product governance. The impact of their products on society, labour relations and environmental concerns are also key risks to monitor.
Whitbread's management of material ESG issues is strong according to Sustainalytics. Human capital management is considered above average with a strong development program in place. The company has appointed a management committee for overseeing ESG issues, but reporting is not in accordance with leading standards. As the owner of the UK's largest hotel chain, we would like to see an improvement in carbon intensity, and clearer targets on reducing its water usage. Further, management of product governance has been called out as average with no evidence that Whitbread's hotels and restaurants have received external quality certifications.
Whitbread key facts
All ratios are sourced from LSEG Datastream, based on previous day’s closing values. Please remember yields are variable and not a reliable indicator of future income. Keep in mind key figures shouldn’t be looked at on their own – it’s important to understand the big picture.
This article is original Hargreaves Lansdown content, published by Hargreaves Lansdown. It was correct as at the date of publication, and our views may have changed since then. Unless otherwise stated estimates, including prospective yields, are a consensus of analyst forecasts provided by LSEG. These estimates are not a reliable indicator of future performance. Yields are variable and not guaranteed. Investments rise and fall in value so investors could make a loss.
This article is not advice or a recommendation to buy, sell or hold any investment. No view is given on the present or future value or price of any investment, and investors should form their own view on any proposed investment.