Revenue grew 22% to $3.1bn ($2.9bn expected), driven by solid procedure growth and a 30% increase in system sales.
Underlying operating profit rose 30% to $1.3bn ($1.1bn expected), as strong sales growth and disciplined cost control helped profits grow faster than revenue.
Cash on hand fell by $1.8bn to $6.8bn over the quarter, as improved cash generation was more than offset by the $2.9bn spent on share buybacks.
Full-year guidance was broadly unchanged, with the procedure growth range tightened from 13.5-15.5% to 14-15%. Underlying gross margin guidance improved slightly to 68.7-69.3%.
The shares fell 7.0% in after-hours trading
Our view
Intuitive Surgical delivered another strong quarter, but sentiment had been recovering ahead of the results. Continued softness in US procedure growth and guidance that failed to lift expectations sparked a negative market reaction.
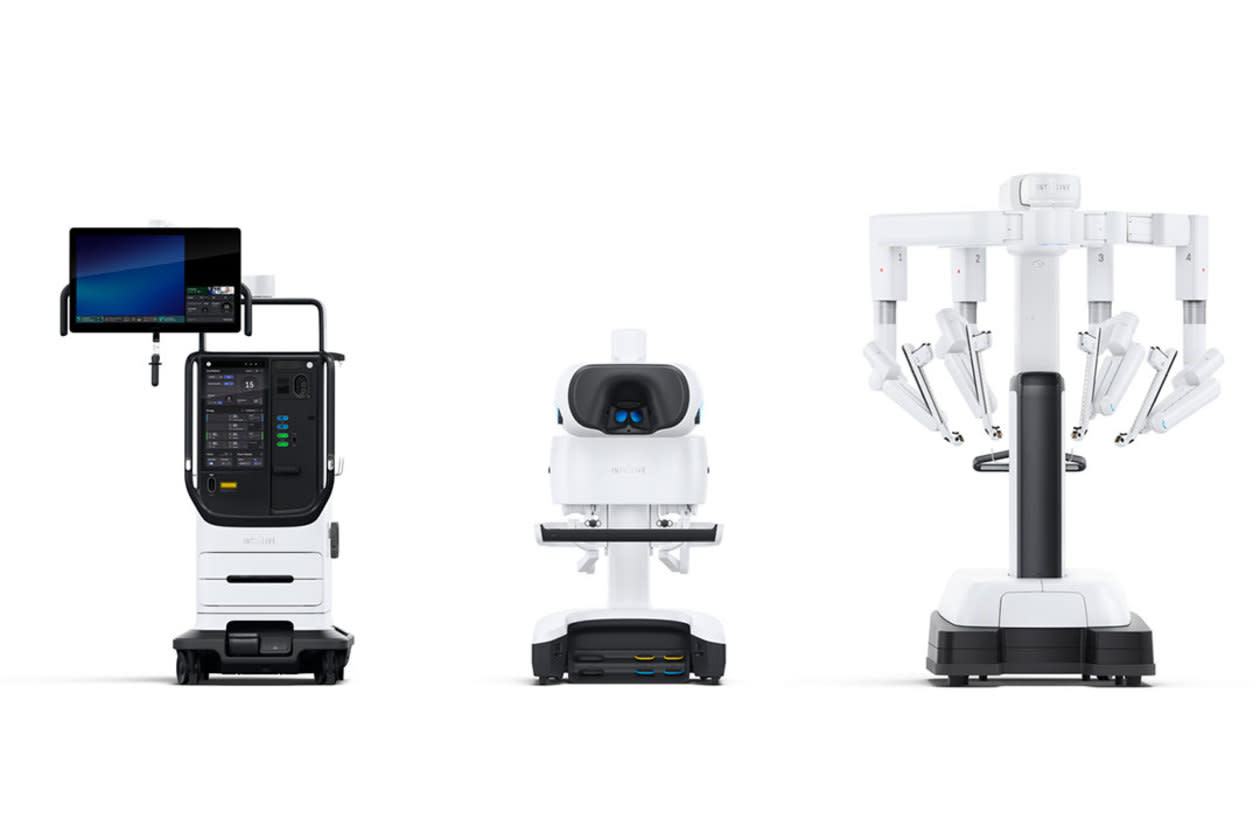
The company dominates the complex field of robotic surgery. Its flagship da Vinci systems cost around $2mn but can offer compelling benefits to healthcare providers and patients, including fewer complications and a lower overall cost of care.
That has driven rapid adoption. Strong system sales are replacing older machines and adding capacity, expanding the installed base from which Intuitive earns recurring income through instruments, accessories and servicing. Greater use of newer Da Vinci 5 systems should support this model, although a $450mn settlement over third-party repairs and servicing introduces some uncertainty around future commercial arrangements and their potential impact on recurring revenues.
US procedure growth remains a relative weak spot, with 10% growth reflecting a particularly tough comparison and some uncertainty around insurance and reimbursement changes. To support longer-term adoption, Intuitive is lowering instrument costs for high-volume procedures such as hernia repair. Alongside mandated cuts in China, this is expected to reduce instrument and accessories revenue per procedure by around 3–5% once fully implemented.
Cost-saving efforts mean that the near-term margin impact should be modest and that these lower prices could expand access to robotic surgery over time. Growth elsewhere remains much stronger, particularly in routine non-cancer procedures, highlighting the opportunity to expand robotic surgery into higher-volume areas beyond its traditional specialist niches.
Innovation is another priority. Ion, its lung-biopsy platform, is gaining ground, and flexible robotic systems could open the door to gastrointestinal surgery. Force-feedback instruments have shown encouraging early clinical results, with scope for wider take-up as availability improves.
Intuitive’s scale and wealth of surgical data provide a strong foundation for using AI to further improve its platform. The group is developing voice controls, automated instrument movement, and advanced imaging, which could simplify procedures for surgeons and make its systems more appealing to hospitals. A strong balance sheet and impressive cash generation allow it to fund innovation, lower customer costs, and return cash through buybacks, although none of this is guaranteed.
The group’s long-term approach should deepen adoption and strengthen its competitive position. The valuation has come under pressure this year, reflecting expectations of slowing growth. But they have a long track record of beating expectations, and we think that the valuation looks attractive if it can continue to deliver. In the near term, though, pricing initiatives could initially weigh on revenue growth, so procedure volumes will need to be closely watched for signs that lower prices are encouraging wider adoption.
Environmental, social and governance (ESG) risk
The healthcare industry is medium/high risk in terms of ESG, depending on subindustry. Across the board, product governance is the most acute risk, with business ethics, labour relations and data privacy also contributing. Providing reasonable access to healthcare as a basic service is also a growing issue, with greater concerns surrounding the social implications of for-profit healthcare companies.
According to Sustainalytics, Intuitive Surgical’s management of ESG risks is strong and often ahead of the industry. Its surgical systems are subject to the relevant safety certifications, complemented by a robust internal product and safety programme. The advanced nature of Intuitive’s technology also requires specialist knowledge. That’s supported by initiatives for talent development and recruitment, reflected in a staff turnover rate below 10%.
Although it manages most material risks better than peers, it falls behind on its approach to eco-friendly product design and end of life product stewardship, although these issues are mentioned in its reporting.
Access to care for patients is another key ESG risk for the sector, and although Intuitive recognises this, its approach could be improved by setting targets and reporting on the progress of its initiatives.
Intuitive Surgical key facts
All ratios are sourced from LSEG Datastream, based on previous day’s closing values. Please remember that yields are variable and not a reliable indicator of future income. Keep in mind that key figures shouldn’t be looked at on their own – it’s important to understand the big picture.
This article is original Hargreaves Lansdown content, published by Hargreaves Lansdown. It was correct as at the date of publication, and our views may have changed since then. Unless otherwise stated estimates, including prospective yields, are a consensus of analyst forecasts provided by LSEG. These estimates are not a reliable indicator of future performance. Yields are variable and not guaranteed. Investments rise and fall in value so investors could make a loss.
This article is not advice or a recommendation to buy, sell or hold any investment. No view is given on the present or future value or price of any investment, and investors should form their own view on any proposed investment.